Planning Wealth Around The Choice To Age In Place
More clients are telling their advisors that their greatest retirement wish is to remain at home as long as possible. That preference has profound implications for portfolio design, risk management, and family decision-making. Aging-in-place is not only a lifestyle choice; it is a complex financial project that spans decades and generations. Advisors who treat it as a central planning objective can better protect both retirement income and family relationships. The result is a wealth plan that supports dignity, safety, and financial stability through every stage of aging.
Reframing Aging-In-Place As A Core Wealth Objective
Many financial plans still treat housing and long-term care as separate topics, which can leave major gaps as clients age. When you frame aging-in-place as a core objective, the home becomes both a cherished residence and a strategic planning asset. This allows you to connect mortgage decisions, renovation timing, and potential downsizing scenarios to the client’s broader wealth picture. It also encourages early conversations about who will help with daily tasks and how that support will be funded. With this mindset, aging-in-place moves from a hopeful wish to a defined, actionable goal.
Advisors can begin by asking clients detailed quality-of-life questions that go beyond investment returns or withdrawal rates. These questions might explore preferred communities, acceptable trade-offs between independence and safety, and tolerance for bringing professionals into the home. The answers shape assumptions around future expenses and the timing of care. They also clarify whether the home is expected to remain in the family or eventually be sold to fund later-stage care. This clarity lets you align investment strategy, liquidity planning, and estate goals with the client’s real vision of aging.
Mapping The True Cost Of Staying At Home
The financial reality of aging-in-place is often underestimated, especially when families assume that Medicare will cover most support needs. In practice, many services that allow a person to remain home, such as personal care aides and household help, may require out-of-pocket funding. Advisors can add value by modeling a range of monthly care costs under different health scenarios. These projections should include both direct care and hidden expenses like increased utilities, transportation help, and technology monitoring tools. With realistic numbers, clients can make deliberate choices rather than reactive ones during a crisis.
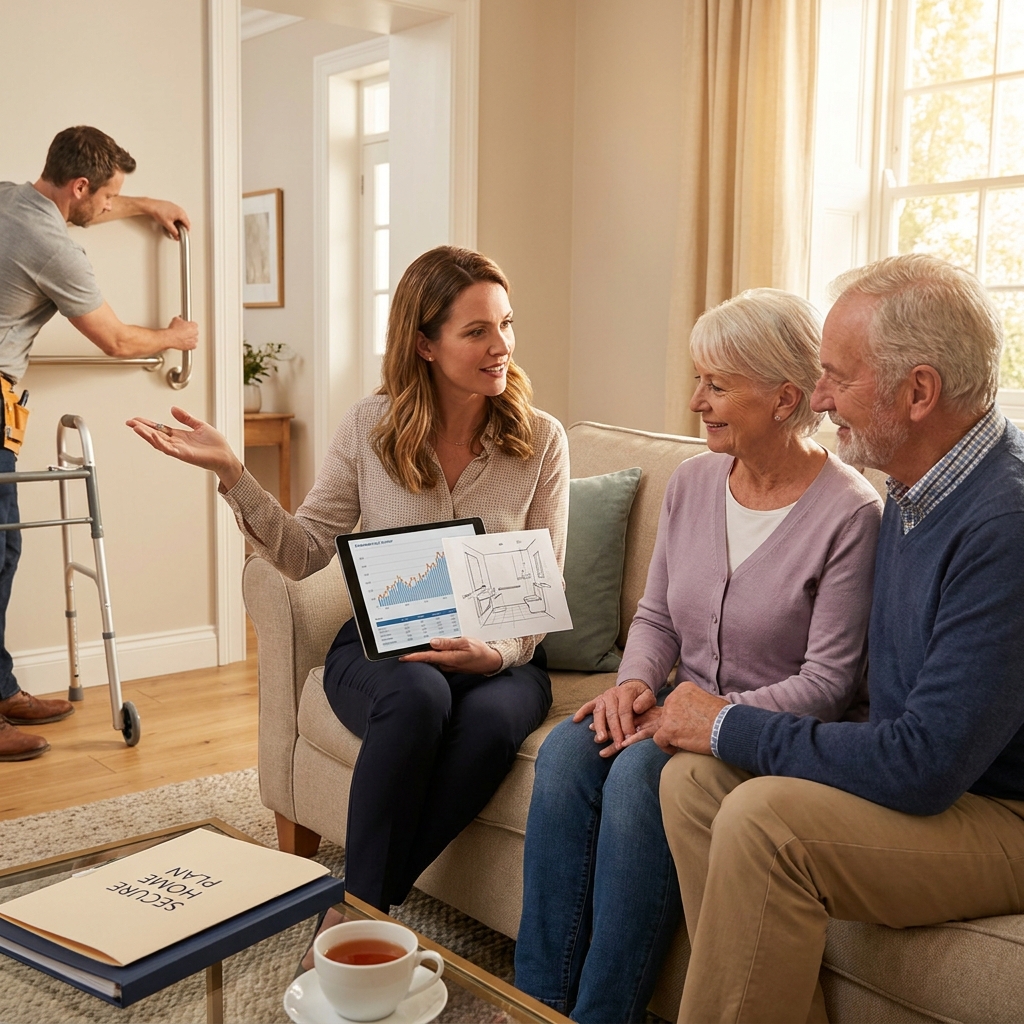
Another key component is planning for home modifications that support safety and accessibility over time. Even relatively modest upgrades like grab bars, improved lighting, or entry ramps carry costs that can add up across many years. Larger projects, such as bathroom remodels, stair lifts, or first-floor bedroom conversions, may compete with other financial goals if they are not anticipated early. Advisors can schedule these upgrades as specific line items within retirement spending plans. By assigning time frames and budgets, you help clients align renovation timing with available cash flow and potential tax-efficient withdrawal strategies.
Funding Strategies For In-Home Care And Long-Term Support
Once realistic costs are outlined, the next step is designing a funding mix that can flex as needs change. This often includes a combination of portfolio withdrawals, dedicated cash reserves, insurance solutions, and sometimes home equity. Advisors can explore long-term care insurance or hybrid life policies where appropriate, matching benefit periods and elimination periods to expected family capacity to provide informal care. Annuities with lifetime income features may also be considered to cover a baseline of predictable care costs. The goal is not a single perfect tool, but a layered funding structure that can adapt over time.
Tax-aware withdrawal strategies become especially important when care costs surge in later years. Coordinating distributions across taxable, tax-deferred, and tax-free accounts can help maintain net spending power while managing marginal tax brackets. Advisors may also evaluate the timing of Roth conversions or capital gain realizations in relation to anticipated care expenses. For some clients, home equity can be positioned as a last-resort reserve, whether through a future sale or carefully structured borrowing. By mapping which dollars are tapped first and why, you reduce the risk that urgent care needs will force poorly timed asset sales.
Designing Support Structures For Family And Professional Caregivers
Caregiver support is both a financial and human issue, and a strong plan recognizes the value of everyone involved. Many adult children assume they can step in freely, only to discover that caregiving significantly disrupts their own careers, savings, and health. Advisors can facilitate open discussions about realistic time commitments, geographic limitations, and emotional capacity within the family. From there, you can help the client budget for supplemental professional caregivers to relieve pressure on relatives. This blended approach can extend the ability to age-in-place while preserving family relationships and economic stability.
Structuring financial recognition for family caregivers can also be part of a thoughtful long-term plan. Some families choose to compensate a primary caregiver using a formal care agreement, which can clarify expectations and reduce resentments. Others may adjust inheritance plans to acknowledge unequal caregiving contributions among siblings. Advisors can run projections showing how different support scenarios affect both the elder’s security and the caregivers’ long-term financial paths. These conversations transform caregiving from an unplanned sacrifice into an intentional, supported role backed by a clear financial strategy.
Coordinating Legal Structures And Decision-Making For Later Life
Aging-in-place and long-term care planning rely on more than cash flow; they also require clear authority for decision-making as health changes. Advisors can encourage clients to keep durable powers of attorney, health care proxies, and living wills current and coordinated with the financial plan. These documents help ensure that someone trusted can manage bills, investment decisions, and care arrangements if the client becomes unable to do so. It is also helpful to document and share the logic behind key financial choices, such as why certain accounts are reserved for care. This transparency can reduce family conflict and hesitation at critical moments.
Trust structures may also play a role, particularly when clients want to protect assets while ensuring access to needed care. While legal counsel should guide the design, advisors can help assess how a trust might interact with investment strategy and beneficiary expectations. Clear communication around trustee responsibilities, distribution standards, and care priorities can keep the plan aligned with the client’s intent. Advisors can maintain a concise summary of these structures alongside the financial projections for long-term care. That way, when health events occur, everyone knows which tools exist and how they support aging-in-place goals.
Keeping The Plan Current As Health, Housing, And Family Needs Change
Aging-in-place and long-term care planning are not single decisions; they are ongoing processes that require periodic recalibration. Advisors can establish specific review triggers, such as a new diagnosis, a hospitalization, or the loss of a spouse or partner. These events often change both the level of support needed and the financial resources available. Regular check-ins can reassess home safety, caregiving capacity, and the sustainability of current spending patterns. Adjustments made early are usually less disruptive than those forced by sudden crises.
Because aging impacts the entire household, plan reviews should include both financial data and qualitative feedback from key family members. Are caregivers feeling overwhelmed, or is professional support still adequate and affordable. Has the client’s preference for remaining at home shifted as mobility or cognition changes. Do recent expenses suggest that a different level of care or a new environment may be safer or more sustainable. By integrating these insights with updated projections, advisors can help clients move confidently through each phase of aging with a clear financial roadmap.