Designing a Retirement Plan That Works Like a Coordinated System
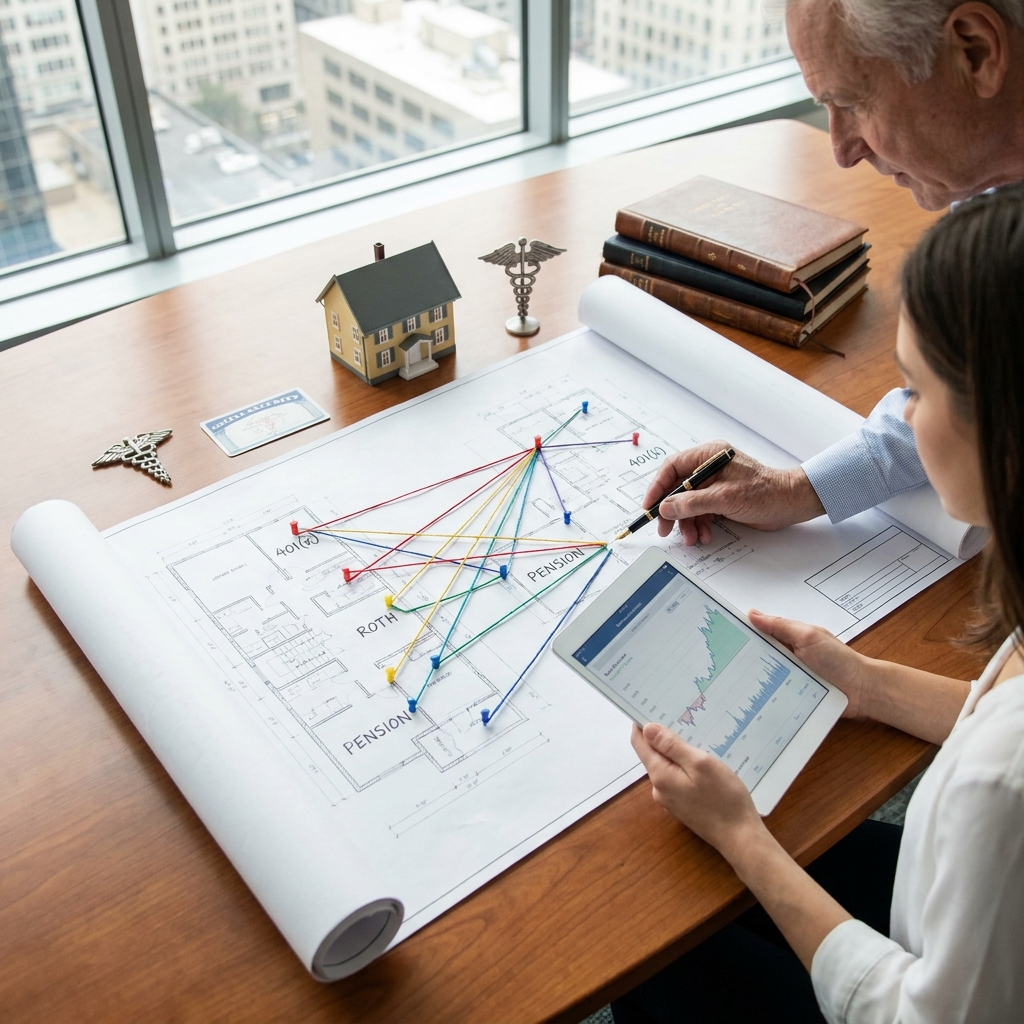
Successful retirement planning in wealth management is less about any one account and more about how every piece works together. For clients, the challenge is not just saving, but sequencing 401(k), Roth IRA, pension, Social Security, and healthcare decisions into a single, coherent strategy. Advisors who frame retirement as a coordinated income system can help clients reduce taxes, preserve flexibility, and protect against longevity risk. That coordination turns scattered accounts into an organized retirement paycheck that can adapt to markets and life events. The result is a plan that feels intentional instead of improvised.
To build that kind of plan, advisors start by mapping out the retirement timeline year by year. This includes when paychecks stop, when each income source starts, and when major expenses such as healthcare premiums and potential long-term care needs may spike. With this timeline in view, financial planners can model cash flows, tax brackets, and portfolio withdrawals under multiple scenarios. That modeling allows clients to see the downstream impact of choices like retiring at 62 versus 67 or claiming Social Security early versus later. The more concrete the projections, the easier it becomes for clients to commit to disciplined saving and informed retirement decisions.
Aligning 401(k) Contributions With Roth IRA Opportunities
Within a coordinated retirement plan, tax-deferred 401(k) assets and tax-free Roth IRA assets play very different but complementary roles. Advisors typically encourage clients to contribute enough to capture the full employer match in a 401(k), because that match can function like an immediate return on contributions. Beyond the match, the decision to prioritize additional 401(k) contributions or Roth IRA funding depends on current and expected future tax brackets. Clients who expect higher tax rates in retirement may benefit from building a larger Roth pool today, even if that means paying more tax in working years. This split allows advisors to manage lifetime tax exposure rather than just minimizing taxes in a single year.
Tax diversification between 401(k) and Roth assets also expands flexibility in retirement income planning. In high-income years during retirement, clients can draw more from Roth accounts to limit taxable income and manage Medicare premium thresholds. In lower-income years, pulling from tax-deferred accounts may be more efficient and can help reduce future required minimum distributions. Advisors can use projections to show clients how shifting just a portion of savings toward Roth contributions or Roth conversions can reshape future tax outcomes. These conversations help clients see their accounts not as separate buckets, but as tools to sculpt a smoother tax profile over decades. That clarity often increases buy-in for disciplined saving strategies.
Positioning Pensions as the Foundation, Not the Entire Plan
For clients who still have access to a defined benefit pension, that income can serve as a stable foundation but rarely covers every retirement need. Advisors start by translating the pension options into an equivalent income stream, comparing single-life, joint-life, and lump-sum choices. Each option carries trade-offs around survivor protection, inflation sensitivity, and investment control. When pensions do not adjust fully for inflation, planners can show how purchasing power erodes across a 25- or 30-year retirement. This analysis helps clients understand that even a strong pension needs to be complemented by personal savings and smart withdrawal strategies.
Deciding between a lifetime pension and a lump-sum rollover into an IRA requires careful modeling. Advisors evaluate the financial strength of the pension provider, the client’s health and family longevity patterns, and their risk tolerance. A lump sum may offer more flexibility and estate value, but it also transfers investment and longevity risk to the client. By comparing projected cash flows under multiple interest-rate and market-return scenarios, planners can demonstrate the range of possible outcomes. This grounded, numbers-driven approach moves the discussion from guesswork to informed choice.
Timing Social Security to Complement Other Income Streams
Social Security is often the most misunderstood piece of a retirement plan, even though it may represent a meaningful share of lifetime retirement income. Advisors add value by reframing the decision from a simple “claim at 62 or 67” question to a coordinated, multi-year income strategy. The choice of when to claim affects not only monthly benefits, but also survivor benefits, tax exposure, and portfolio withdrawal rates. For clients with substantial savings, delaying benefits can reduce pressure on investment accounts in later years, when healthcare costs and longevity risk tend to rise. For others, claiming earlier may preserve portfolio assets for growth or legacy goals.
Social Security planning becomes even more powerful when integrated with 401(k) and Roth withdrawal strategies. In some cases, advisors may recommend temporarily using tax-deferred withdrawals before benefits begin, intentionally filling up lower tax brackets early in retirement. This can reduce the size of future required minimum distributions and lower the percentage of Social Security benefits that will be taxed. In other cases, clients may rely more heavily on taxable or Roth withdrawals while delaying benefits to increase the guaranteed income floor. Scenario analysis lets clients see side-by-side comparisons of lifetime income under different claiming ages, turning a vague decision into a clear, data-backed strategy.
Using Healthcare and Longevity Projections to Set Realistic Targets
Healthcare is one of the largest and least predictable retirement expenses, so projections in this area are central to any serious wealth management plan. Advisors begin by mapping the transition from employer coverage to Medicare, including the gap years if clients retire before eligibility. This includes estimates for premiums, out-of-pocket costs, and supplemental coverage. Planners then layer in potential long-term care needs, which can significantly alter cash-flow requirements and legacy goals. By stress-testing the plan against higher-than-expected healthcare inflation, advisors can identify how much cushion is needed in retirement savings.
Longevity assumptions are equally important in setting sustainable withdrawal rates. Rather than relying on average life expectancy, advisors often plan for clients to live well into their 90s, particularly when there is a family history of long life. This forward-looking assumption protects clients from underestimating the number of years their income must last. With a longer timeline in mind, healthcare projections become not just a line item, but a driver of asset allocation and income strategy. Advisors can then help clients decide whether to fund healthcare contingencies within their portfolio, through insurance solutions, or a combination of both. This proactive planning turns a major source of anxiety into a manageable component of the overall strategy.
Orchestrating Withdrawals Into a Sustainable Retirement Paycheck
Once the building blocks are in place, the real craft of retirement planning lies in orchestrating withdrawals across all accounts. Advisors aim to create a predictable monthly paycheck that matches the client’s lifestyle while preserving flexibility for unexpected expenses. A common approach is to pair stable income sources such as pensions and Social Security with a dynamic withdrawal strategy from investment accounts. Taxable accounts, 401(k)s, and Roth IRAs are tapped in varying proportions depending on tax brackets, market conditions, and healthcare costs. This approach allows advisors to smooth after-tax income even when markets are volatile.
Over time, withdrawal strategies are adjusted as tax laws change, healthcare needs evolve, and clients move through different retirement stages. Early retirement years might emphasize portfolio withdrawals to bridge the gap before Social Security or pension benefits begin. Mid-retirement often focuses on managing required minimum distributions and avoiding unnecessary tax spikes. Later years may prioritize simplifying accounts and ensuring that income streams are easy to manage if a spouse or partner needs to take over. Through regular reviews and updated projections, advisors can keep the retirement paycheck aligned with both the markets and the client’s life.